If you’ve been watching the housing market across the Wasatch Front over the last two months, it’s felt like a relentless uphill climb. Mortgage rates steadily marched to a three-year high, leaving many local buyers and sellers wondering when the ceiling would finally be reached.
That ceiling just arrived.
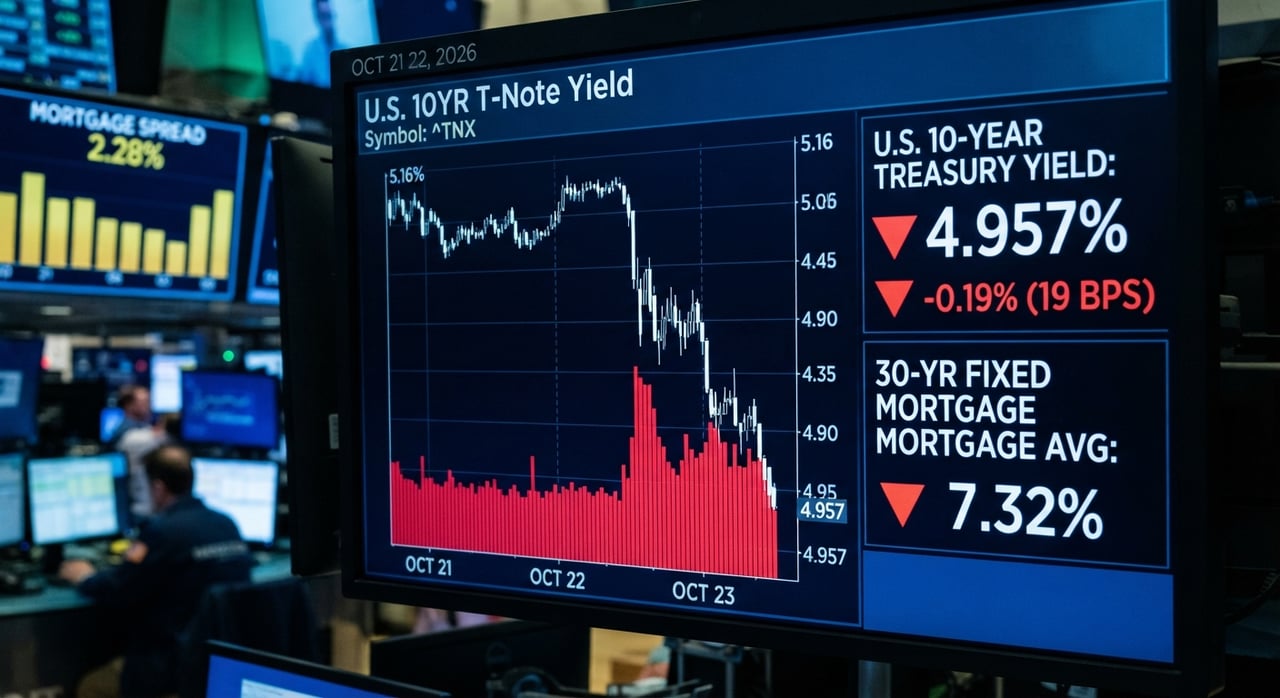
On October 22, 2026, the U.S. 10-Year Treasury yield saw its sharpest one-day decline in over a year, tumbling down to 4.957% and breaking below the key 5% threshold. Because long-term fixed mortgage rates are closely tied to this specific Treasury yield, the impact on home loans was instantaneous.
For the first time since late August, the upward surge halted, pulling the national 30-year fixed mortgage average down to 7.32% (from the previous week's 7.40% high).
While a shift from 7.40% to 7.32% might seem small on paper, the underlying mechanics tell a much bigger story about where our local market is heading—and how you should play your cards right now.
The "Hidden Gap" Keeping Local Rates Elevated
A common question I'm hearing from clients right now is: “If the 10-year Treasury yield is back down under 5%, why are mortgage rates still stuck in the low 7s?”
The answer comes down to something called the mortgage spread. This is the margin that lenders add on top of the baseline Treasury yield to protect themselves against market volatility and inflation. Historically, this spread stays around 1.6% to 2.0%.
Right now, because of global economic uncertainty, lenders are staying incredibly cautious. The current spread is hovering at an elevated 2.28 percentage points.
Why this matters to you: This gap means that mortgage rates are artificially high due to lender caution, not just baseline economics. The moment the broader economic fog clears, there is significant structural room for mortgage rates to ease downward along the Wasatch Front, independent of what the Federal Reserve does next.
What This Means If You Are Buying Along the Wasatch Front
The recent rate spike sidelined a lot of great local buyers, which means competition temporarily cooled off in highly competitive neighborhoods from Sandy down to Spanish Fork. This sudden pullback in rates creates a unique tactical window. Let’s look at how the math actually breaks down across our two major counties: [1]
📍 The Utah County Breakdown
With a median home sale price hovering around $528,732, a buyer locking in last week's peak rate of 7.40% was looking at a principal and interest payment of roughly $3,660.83 per month. At this week's adjusted 7.32%, that same monthly payment drops to $3,632.02. (From Redfin)
- The Local Impact: That saves you roughly $28.81 every single month—or over $10,300 in interest saved over the life of your loan just by timing the market shift correctly.
📍 The Salt Lake County Breakdown
For a single-family or traditional home at Salt Lake County’s broader median price point of $565,000, shifting from 7.40% down to 7.32% drops your monthly principal and interest payment from $3,911.95 to $3,881.16. (From Redfin)
- The Local Impact: That’s an immediate $30.79 per month back in your pocket, cutting out more than $11,000 in lifetime interest costs.
- Re-Price Your Pre-Approval: If you paused your search two weeks ago in Orem, Provo, or Salt Lake City, call your lender today. Even a fractional drop changes your debt-to-income numbers and expands your local purchasing power. [1, 2]
- Marry the House, Date the Rate: With the mortgage spread as high as it is, the opportunity to refinance into a lower bracket over the next 12 to 24 months remains highly probable. Buying now lets you lock in today's softer home prices before a larger rate drop brings the crowd back to local open houses.
What This Means If You Are Selling in Utah or Salt Lake County
If your home is currently listed or you are preparing to launch it onto the market, this market turn is excellent news for your active buyer pool.
- A Wave of Weekend Shoppers: Slight rate drops instantly trigger automated alerts on real estate apps for buyers tracking specific Utah ZIP codes. Expect an uptick in weekend open house traffic and showing requests.
- The Clock is Ticking: The Federal Reserve meets on October 28. Market stability right now is a window of opportunity, not a permanent guarantee. Pricing your home accurately against local comps right now ensures you capture the highly motivated buyers who are rushing to lock in this week's rate reprieve.
Strategy Wins Every Market
The headline news will always try to paint the housing market with a broad brush, but real estate is inherently local. Volatility introduces opportunities for buyers and sellers who know how to read the numbers.
Want to see the exact math for your neighborhood or specific budget?
Whether you want to know how this rate shift alters your monthly payment blocks on a home in American Fork, or you want a customized equity evaluation to see what your net proceeds look like as a seller in Salt Lake City, I am here to navigate the numbers for you.
Whether you want to know how this rate shift alters your monthly payment blocks on a home in American Fork, or you want a customized equity evaluation to see what your net proceeds look like as a seller in Salt Lake City, I am here to navigate the numbers for you.
[Click here to schedule a quick, zero-pressure strategy call] or send me a direct message through the site!
Christine Alleman 801-687-6596